Male breast reduction, surgery to treat gynecomastia (enlarged male breast tissue), sits in a gray area between cosmetic and medically necessary procedures. That gray area is exactly why insurance coverage questions come up so often. This guide walks through how coverage typically works, what determines whether your case might qualify, the practical steps for finding out where you stand, and what your options look like if coverage doesn't come through. If you're also researching candidacy and what recovery actually looks like, our companion post on male breast reduction candidacy and recovery covers that side of the decision in depth.
Cosmetic vs. Medically Necessary: Why It Matters
Insurance companies generally divide breast reduction surgery into two categories, and understanding the distinction is the single most useful thing you can do before calling your insurer.
Cosmetic gynecomastia surgery is performed primarily to improve appearance, without a documented underlying medical condition or significant physical symptoms. This is typically not covered and is treated as an out-of-pocket cosmetic procedure, similar to how insurers treat elective cosmetic surgery generally.
Medically necessary gynecomastia surgery is performed to address a diagnosed condition or documented physical symptoms, and insurers vary widely in how strictly they define this. This is the category where coverage becomes possible, though never guaranteed, and where the specific documentation you and your physician assemble makes a real difference in the outcome.
It's worth understanding that this isn't a judgment about how much your gynecomastia bothers you personally, insurers are specifically looking for objective, documentable criteria: a diagnosis, physical symptoms, duration, and ruled-out alternative causes. Two men with visually similar gynecomastia can have very different insurance outcomes depending entirely on what's documented in their medical records.
What Insurers Typically Look For
While every insurance plan has its own criteria, common requirements for considering gynecomastia surgery medically necessary include:
A documented diagnosis of gynecomastia, not just excess fat, which is typically treated as cosmetic. This distinction matters clinically as well as for insurance purposes: true gynecomastia involves glandular breast tissue enlargement, which can sometimes be confirmed through physical exam alone, but in ambiguous cases may involve imaging such as an ultrasound or mammogram to distinguish glandular tissue from fatty tissue (pseudogynecomastia).
Persistent symptoms such as pain, tenderness, or skin irritation. Insurers generally want to see that the condition causes physical discomfort, not solely a cosmetic concern, though psychological impact is sometimes considered as supporting, secondary documentation rather than a primary qualifying criterion on its own.
Gynecomastia that has persisted for a defined period, often a year or more, without resolving through other treatment. Many insurers want documentation that the condition is chronic rather than a recent, potentially self-resolving change, since gynecomastia can sometimes fluctuate or resolve on its own, particularly in adolescents or in cases linked to a temporary medication or hormonal shift.
Ruling out underlying causes like hormonal imbalances, certain medications, or other medical conditions, sometimes requiring documentation from an endocrinologist or primary care physician. This step matters both medically and for insurance purposes: if gynecomastia is being caused by an active, treatable underlying condition or medication, insurers may want that addressed first, or may want documentation that it's been ruled out or is not expected to resolve the condition on its own.
In some cases, a required BMI range or documentation that the condition isn't related to obesity, since insurers may classify weight-related breast tissue differently, treating it more like pseudogynecomastia (fatty tissue) than true glandular gynecomastia, which affects how the claim is categorized.
Failed conservative treatment, where applicable. For some insurers, particularly if the gynecomastia is linked to a specific reversible cause, documentation that appropriate non-surgical steps were tried first (such as addressing a causative medication, where medically appropriate) can strengthen a medical necessity case, though this varies considerably by plan and isn't a universal requirement.
Steps to Find Out If You Might Qualify
1. Get a formal evaluation and diagnosis. Start with your primary care physician or an endocrinologist to document the condition, its duration, and any symptoms. This first step matters more than almost anything else in the process, since your entire insurance case is built on this documentation.
2. Request a letter of medical necessity. If your gynecomastia is linked to a diagnosed cause or ongoing symptoms, your physician may be able to write a letter supporting medical necessity for your insurer. A strong letter typically includes the diagnosis, duration of the condition, documented symptoms, any underlying causes that were evaluated and ruled out or addressed, and a clear clinical recommendation for surgical treatment.
3. Call your insurance provider directly. Ask specifically about their gynecomastia and male breast reduction policy, what documentation they require, and whether prior authorization is needed before surgery. It's worth asking for their specific medical policy document by name if one exists, many major insurers publish detailed clinical criteria for gynecomastia surgery, and having the exact criteria in hand makes it much easier to know what documentation to gather.
4. Consult with your plastic surgeon's office. Many practices have staff experienced in insurance pre-authorization and can tell you, based on your case and insurer, how likely approval is and what paperwork to gather. Surgical practices that regularly handle gynecomastia cases often have a good working sense of which insurers in the area tend to approve these claims and under what specific circumstances.
5. Understand your appeal options. If your initial claim is denied, insurers typically have an appeals process, and additional documentation, sometimes a more detailed letter from your physician, additional imaging, or documentation of symptom duration, can sometimes change the outcome. Ask your surgeon's office and your physician's office whether they're able to assist with an appeal if your first request is denied.
6. Confirm what "covered" actually means before surgery. Even when a claim is approved, ask specifically what's included: is it the surgeon's fee only, or does it also cover anesthesia and facility fees? Some approvals cover a portion of the total cost rather than the entire procedure, so understanding your specific coverage details before surgery avoids unexpected bills afterward.
If Your Surgery Isn't Covered
If your case doesn't meet your insurer's criteria for medical necessity, gynecomastia surgery is still one of the more accessible cosmetic procedures for many patients, and most practices offer:
Financing and payment plans that spread the cost over monthly installments, making the out-of-pocket total more manageable even without insurance coverage. Learn more about payment methods and patient financing available through the practice.
A clear, itemized quote after consultation, so you know the full cost upfront, including surgeon's fee, anesthesia, and facility costs, rather than encountering surprise charges after the fact.
Combination options if you're also considering liposuction or other body contouring, which may affect overall pricing, since gynecomastia surgery sometimes involves a liposuction component to address the fatty tissue portion alongside glandular tissue removal.
It's also worth knowing that many men who don't qualify for insurance coverage still find the procedure worthwhile as a self-pay decision, particularly given how significantly gynecomastia can affect daily comfort, clothing choices, and confidence around physical activity, even when it doesn't meet a specific insurer's technical criteria for medical necessity.
What to Bring to Your Consultation
To get the most useful guidance at your first visit, bring:
- Any prior diagnosis or documentation from your physician, including notes from any prior imaging or evaluation
- A list of current medications, since some medications are linked to gynecomastia, and this information matters both for surgical planning and for the medical necessity conversation
- Your insurance card and plan details, even if you're unsure whether it will apply, so your surgeon's office can check your specific benefits
- A summary of how long you've had symptoms and how they've changed over time, since duration and symptom history are often central to the medical necessity determination
- Any relevant family or personal medical history that might relate to hormonal factors, since this can be relevant to both diagnosis and the insurance documentation process
Understanding the Difference Between Gynecomastia and Related Conditions
Part of what makes the insurance conversation complicated is that "male breast reduction" is sometimes used loosely to describe a few related but clinically distinct situations, and insurers treat them differently.
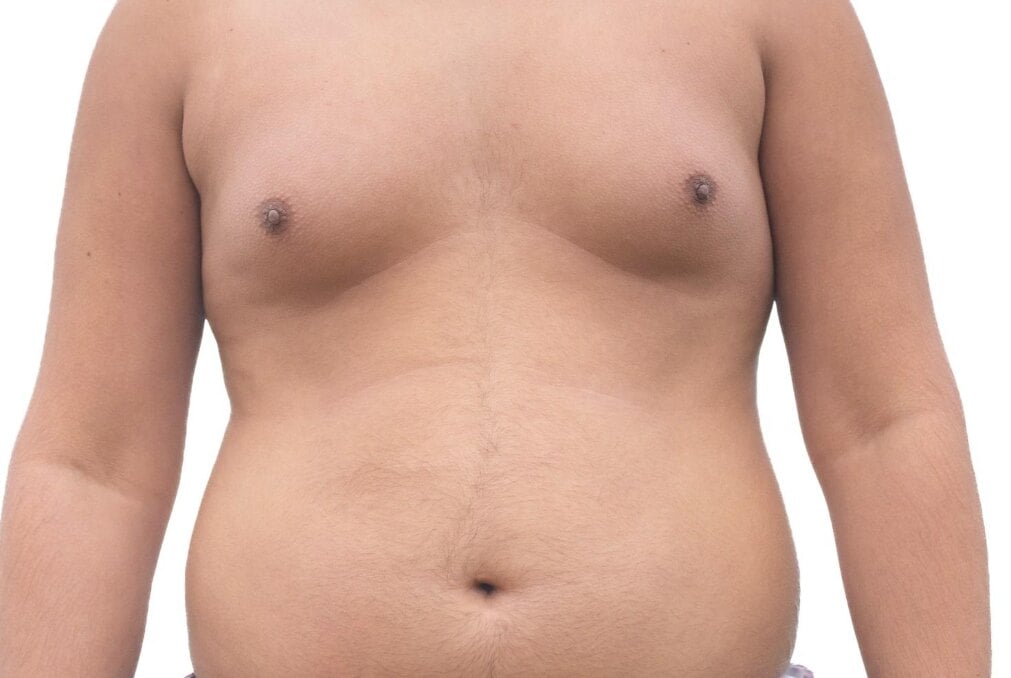
True gynecomastia involves actual glandular breast tissue enlargement, often linked to hormonal factors, certain medications, or in some cases no clearly identifiable cause. This is the category most likely to have a path toward medical necessity documentation.
Pseudogynecomastia, sometimes called lipomastia, refers to fat deposits in the chest area without significant glandular tissue enlargement, often related to overall body weight. Insurers typically treat this as a cosmetic concern regardless of how much it visually resembles true gynecomastia, since the underlying tissue and clinical significance differ.
Combined presentations, where both glandular tissue and fatty tissue contribute to the appearance, are actually quite common, and your surgeon's evaluation, sometimes supported by imaging, helps clarify which component predominates in your specific case. This distinction affects both your surgical plan (whether liposuction alone might be appropriate, versus glandular tissue excision, versus both) and your insurance conversation.
Questions Worth Asking Your Insurance Company Directly
When you call your insurer, having a specific list of questions ready makes the call far more productive than a general inquiry about "coverage for gynecomastia surgery." Consider asking:
- "Do you have a written medical policy specifically for gynecomastia surgery or male breast reduction? Can you send me a copy or point me to it?"
- "What specific diagnostic codes and documentation do you require to consider this medically necessary rather than cosmetic?"
- "Is prior authorization required before surgery, and how long does that process typically take?"
- "Does coverage, if approved, include the surgeon's fee, anesthesia, and facility costs, or only certain components?"
- "What is your appeals process if my initial request is denied, and what additional documentation tends to strengthen an appeal?"
- "Are there in-network requirements I need to be aware of for the surgeon, anesthesiologist, or facility?"
Write down the name of whoever you speak with and the date of the call, and ask for a reference number if one is available. Insurance conversations sometimes involve conflicting information from different representatives, and having a paper trail makes it easier to follow up or escalate if needed.
Understanding Medical Necessity Documentation in More Detail
Since medical necessity determinations hinge so heavily on documentation, it's worth understanding what a strong record typically includes, beyond just a diagnosis.
Duration and consistency of symptoms. Insurers generally respond better to documentation showing a consistent pattern over time, physician notes from more than one visit, rather than a single evaluation performed shortly before the surgery request. If you've mentioned gynecomastia-related discomfort to a physician in the past, even in passing, mentioning this history (and asking your physician to note it if it's not already documented) can help establish the timeline insurers look for.
Specificity of symptoms. General statements like "bothers the patient" tend to carry less weight than specific, physical descriptions: persistent tenderness, pain with certain movements or clothing, skin irritation or chafing in the affected area. Insurers are looking for documentation that reads as a genuine medical complaint, not a cosmetic preference framed in medical language.
Evidence that alternative causes were considered. Documentation showing that your physician evaluated for hormonal causes, reviewed your medication list for known gynecomastia-associated drugs, and considered your overall health context tends to support a stronger medical necessity case than a diagnosis made without this broader evaluation.
Consistency between your surgeon's documentation and your primary physician's documentation. If your surgeon's assessment and your physician's notes tell a consistent, aligned story about your diagnosis, symptoms, and history, this generally supports a cleaner insurance review than documentation that seems inconsistent or incomplete between providers.
Self-Pay Cost Factors to Understand
If insurance coverage doesn't come through, either partially or at all, it helps to understand what actually drives the total self-pay cost of male breast reduction, so the number you're quoted makes sense rather than feeling arbitrary.
Extent of glandular tissue vs. fatty tissue involvement. Cases requiring glandular tissue excision in addition to liposuction are generally more involved surgically than cases where liposuction alone can address the concern, which can affect both surgical time and overall cost.
Whether skin excision is needed. In cases involving significant skin laxity, often seen after substantial weight loss, additional skin removal may be part of the surgical plan, which adds complexity and cost compared to a straightforward liposuction-and-excision approach.
Anesthesia and facility fees, which are billed similarly to other outpatient surgical procedures and typically scale with the length and complexity of the surgery rather than being a flat, fixed amount regardless of the specific case.
Post-operative garments and follow-up care, which are sometimes included in a practice's quoted surgical fee and sometimes billed separately, worth clarifying directly so your total cost picture is accurate and complete.
Ask your surgeon's office for a clear, itemized breakdown during your consultation so you understand exactly what's included in your specific quote, rather than comparing a single total number across different practices without knowing what each number actually includes.
The Emotional Side of Gynecomastia, and Why It's Worth Addressing Regardless of Coverage
While insurance conversations necessarily focus on clinical documentation and physical symptoms, it's worth acknowledging directly that gynecomastia often carries a significant emotional and social weight for the men living with it, avoiding certain clothing, activities like swimming or working out shirtless, or physical intimacy. This impact is real even in cases where an insurer's specific criteria don't classify it as medically necessary, which is precisely why so many men pursue this procedure as a self-pay decision when coverage doesn't come through.
None of this is meant to suggest the insurance conversation doesn't matter or shouldn't be pursued thoroughly, it absolutely should, since coverage can meaningfully reduce the financial burden for patients whose case qualifies. But it's worth going into your consultation understanding that a denial isn't a statement about whether your concern is valid or worth addressing, it's simply a reflection of how insurance medical necessity criteria are specifically defined, which is a narrower standard than "this significantly affects my daily life and confidence."
A Realistic Timeline for the Insurance and Surgical Process
Patients often want to know roughly how long the entire process, from first physician visit to surgery, tends to take when pursuing insurance coverage. While this varies considerably by individual case and insurer, a rough general framework looks something like this:
Initial physician evaluation and diagnosis: typically one to a few visits, depending on whether additional testing or imaging is needed to confirm the diagnosis and rule out other causes.
Gathering documentation and, if applicable, a letter of medical necessity: this can take anywhere from a few days to a few weeks depending on your physician's availability and how much history needs to be compiled.
Insurance submission and pre-authorization review: often several weeks, sometimes longer, depending on the specific insurer's process and whether additional information is requested during review.
Appeal, if the initial request is denied: this adds additional time, often another several weeks, depending on the complexity of the appeal and how quickly additional documentation can be gathered.
Scheduling surgery once approved (or once you decide to proceed as self-pay): this depends on your surgeon's schedule and your own availability, and is generally the most flexible part of the timeline once the insurance question is resolved one way or the other.
Given this, patients who know they want to pursue insurance coverage are generally well served by starting the physician evaluation and documentation process as early as possible, well before they're ready to schedule surgery, since the insurance timeline often ends up being the longest single stretch in the overall process.
Frequently Asked Questions
Is gynecomastia surgery ever covered by insurance?
Yes, in some cases, if the condition is diagnosed as medically necessary rather than cosmetic. Coverage depends entirely on your specific insurer's criteria and your documented medical history.
What's the difference between gynecomastia and chest fat from weight gain?
Gynecomastia refers to actual glandular breast tissue enlargement, often linked to hormonal factors, and is diagnosed through physical exam or imaging. Fat deposits from weight gain are a different issue, sometimes called pseudogynecomastia, and are typically treated as cosmetic by insurers, even though the visual result can look similar.
How long does the insurance approval process usually take?
This varies significantly by insurer, but pre-authorization processes for gynecomastia surgery often take several weeks once all required documentation is submitted, so starting early is worthwhile if you plan to seek coverage.
Can I still get surgery if my insurance denies coverage?
Yes, many patients pursue gynecomastia surgery as a self-pay cosmetic procedure with financing options if their claim isn't approved.
What kind of doctor should diagnose my gynecomastia for insurance purposes?
Your primary care physician can typically make an initial diagnosis and referral, and in some cases an endocrinologist may be involved to help rule out or identify hormonal causes, which can strengthen your documentation for insurance purposes.
Do I need imaging like an ultrasound before insurance will consider covering surgery?
Some insurers require imaging to confirm glandular tissue enlargement and distinguish it from fatty tissue, though this varies by plan. Your physician or surgeon's office can advise whether your specific insurer requires this step.
Will insurance cover the entire cost of my surgery if approved, or just part of it?
This varies by plan and case. Some approvals cover the full procedure, while others cover only certain components, such as the surgeon's fee but not facility or anesthesia costs. Confirm the specific scope of your coverage before surgery to avoid unexpected charges.
What if my gynecomastia is caused by a medication I'm taking?
If a specific medication is identified as a likely cause, your physician may recommend addressing that first, where medically appropriate, since some insurers want this step documented as part of the medical necessity case. This should always be discussed with the prescribing physician before making any medication changes.
Ready to Discuss Your Options?
Whether or not insurance ends up covering part of your procedure, the most useful next step is a consultation where your specific case, documentation, and options can be reviewed directly. Explore the male breast reduction service page, read more about candidacy and recovery, review payment methods and patient financing, or schedule a consultation to get started.
This article is for general informational purposes and does not constitute medical or insurance advice. Coverage varies by insurer and individual plan — confirm your specific benefits directly with your insurance provider and consult Dr. Ayala's office for a personalized evaluation.